Exploring high-potential gold, copper and silver assets across 7,500 hectares in Northern Sweden, within the world-class Skellefteå volcanogenic massive sulphide (VMS) district, one of Europe's most prolific mining regions for over a century.
Building a diversified mining portfolio through strategic investments across Europe.
Gold, copper, and silver share a deep geological relationship. Some of the largest mining operations in the world produce all three metals simultaneously from the same deposit, a geological reality that has long made polymetallic projects among the most economically compelling assets in the entire mining industry.
Sweden is consistently ranked among the top ten mining jurisdictions in the world. In the Fraser Institute's 2025 Annual Survey of Mining Companies, the global benchmark for mining investment attractiveness, Sweden ranked in the top 10 globally, alongside Nevada, Ontario, Saskatchewan, and Norway. Sweden and Norway were the only two European jurisdictions to achieve this distinction, reinforcing Sweden's position as the premier mining destination on the continent.
Sweden offers what few mining jurisdictions can match: world-class geological endowment combined with political stability, regulatory transparency, predictable permitting, excellent infrastructure (roads, rail, ports, and abundant hydroelectric power), a highly skilled workforce, and membership in the European Union.
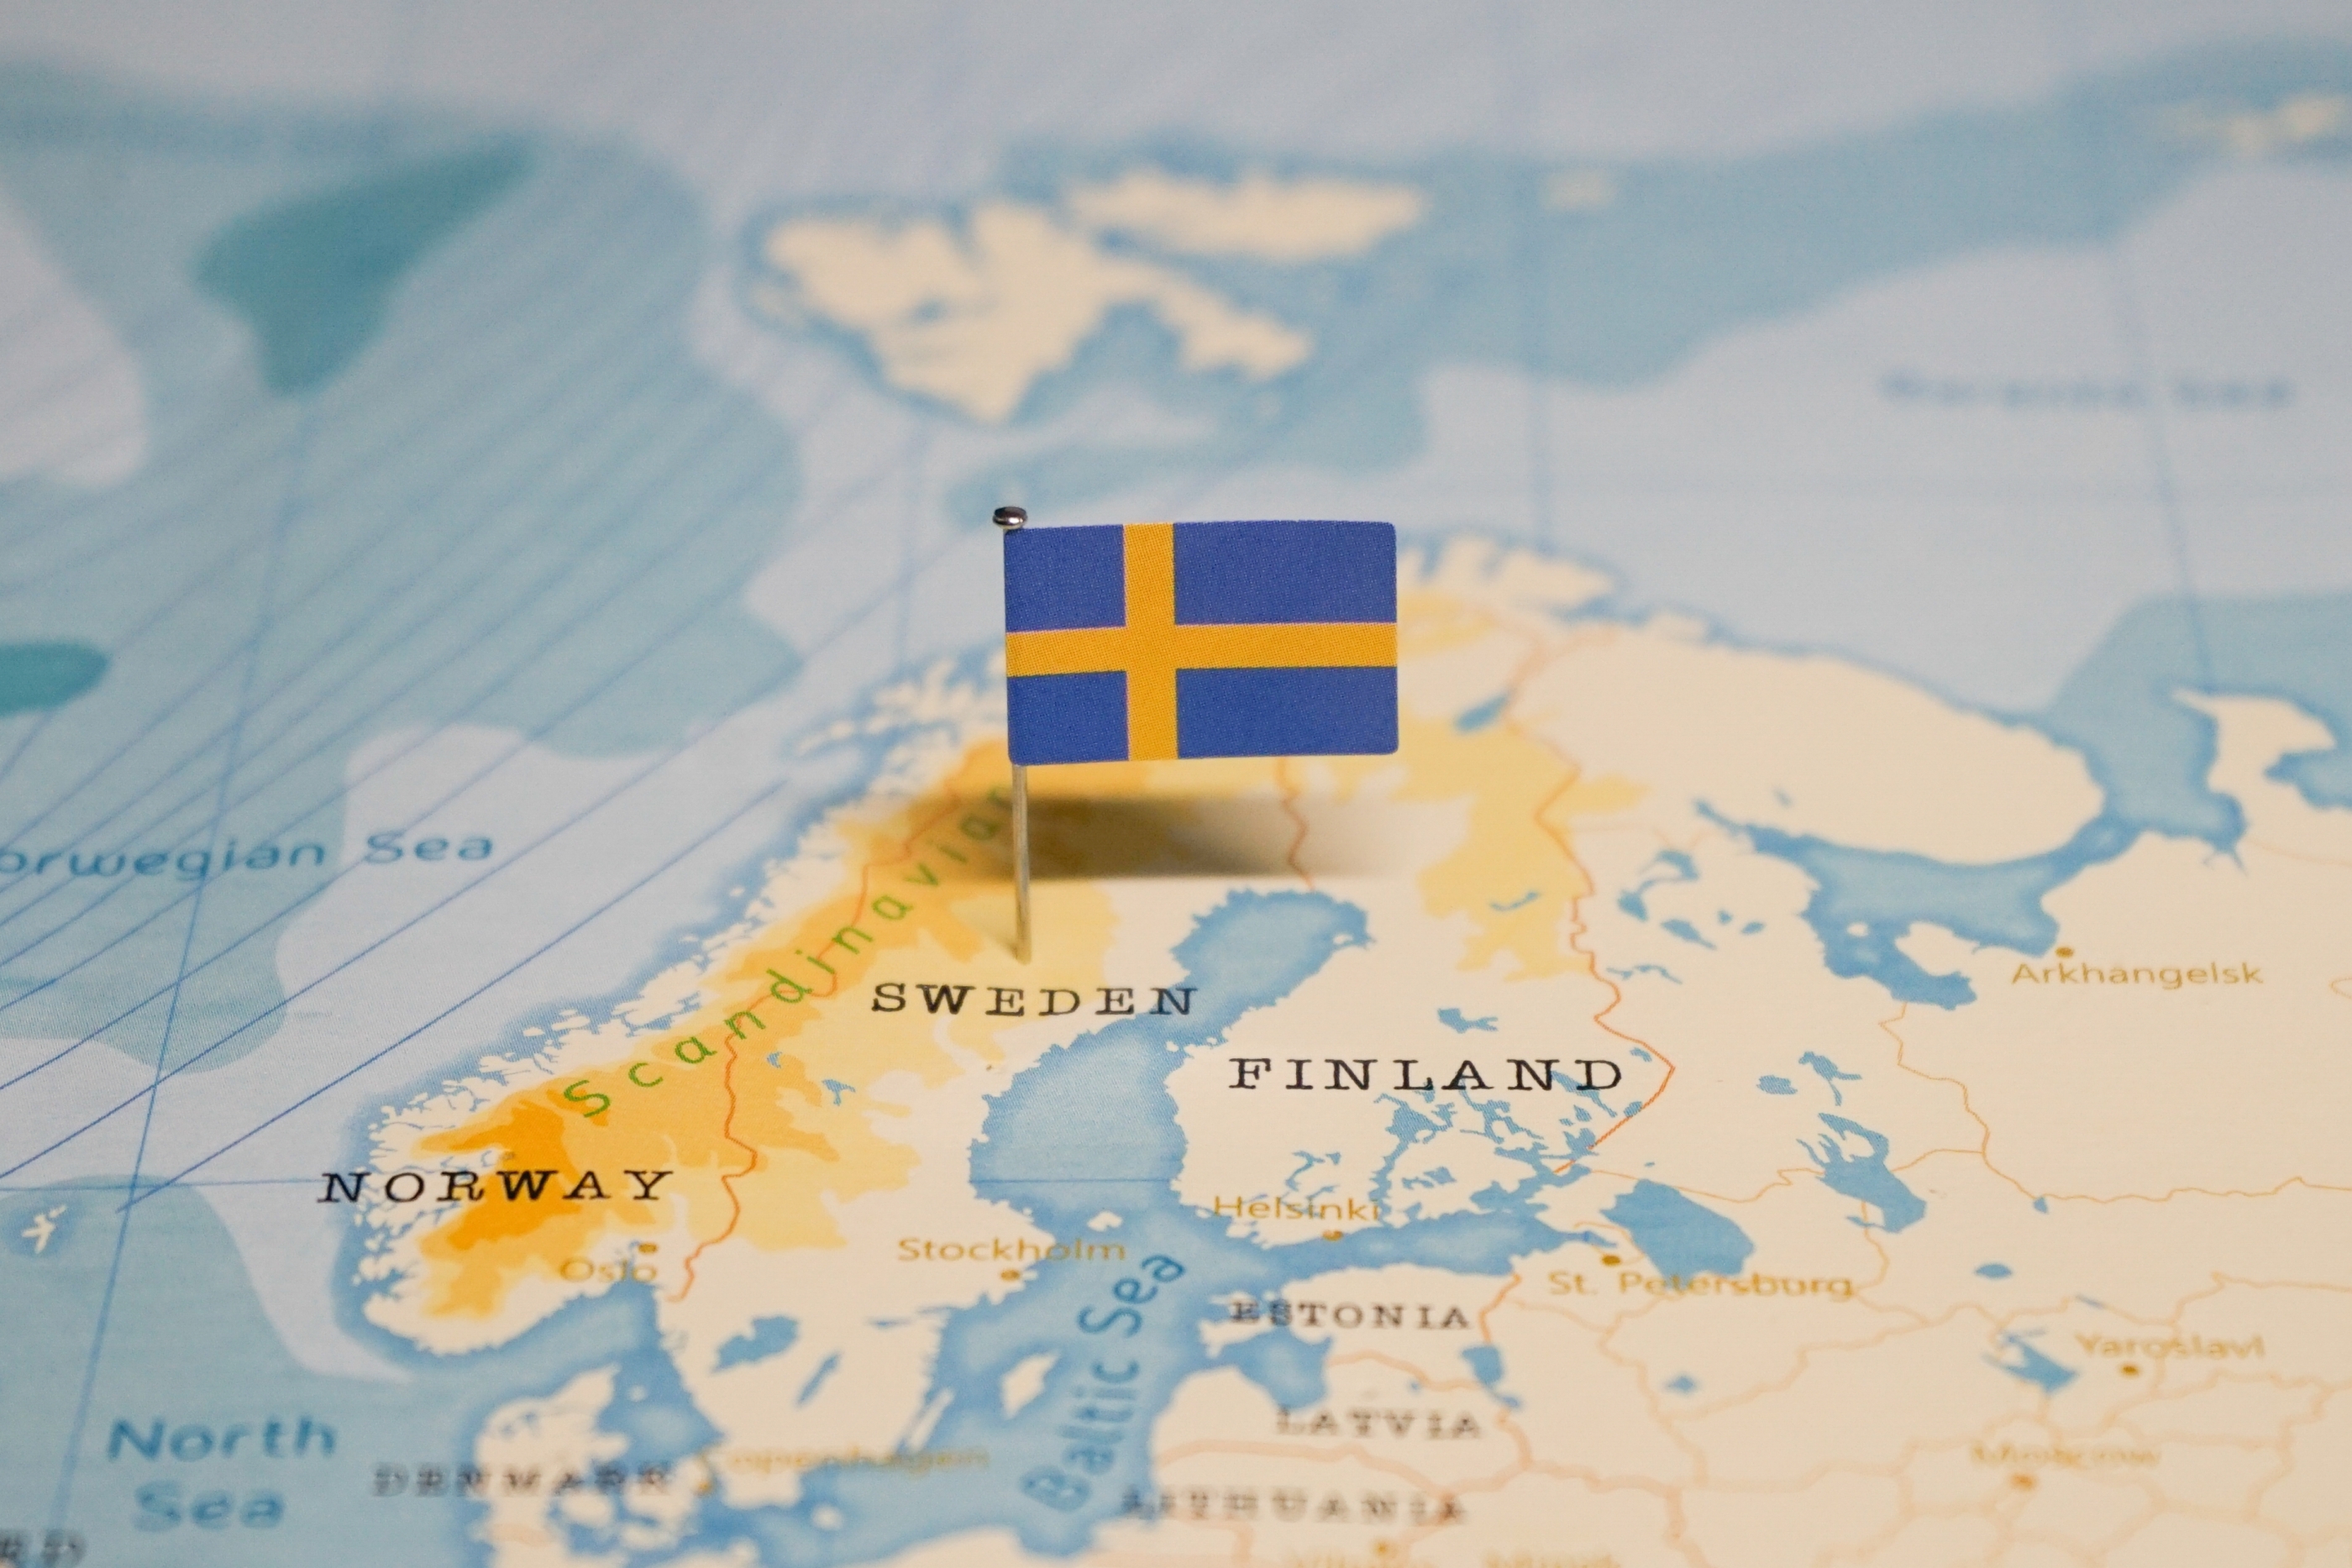
Sweden's Skellefteå mining district is one of Europe's most important metallogenic provinces. Since mining began in the district in the 1920s, the area has produced significant quantities of gold, copper and silver from nearly 30 mines, and remains one of the continent's most productive sources of precious, base and technology-critical metals. The original Boliden mine alone produced 128 tonnes of gold, 411 tonnes of silver and 118,000 tonnes of copper over its operating life, a polymetallic signature that continues across the district to this day.
The Geological Survey of Sweden (SGU) maintains one of the world's most comprehensive geological databases, providing explorers with decades of publicly available geophysical, geochemical, and geological mapping data.
A fundamental shift is underway in European capital allocation. Driven by the EU Critical Raw Materials Act, escalating geopolitical tensions, and the urgent need for mineral sovereignty, European institutional and retail investors are increasingly directing capital toward domestic and EU-allied mining projects.
Scandinavia has emerged as the primary destination for this capital, with investment patterns shifting toward regions that combine favourable geology with institutional stability. The EU's RESourceEU Action Plan, launched with a €3 billion investment drive, is designed to accelerate critical mineral extraction, processing, and recycling within the European Union, while the European Investment Bank has committed a further €2 billion to European minerals, creating a structural tailwind for European-listed mining companies operating on EU soil.
Europe's defence rebuild is reinforcing this shift. With NATO members committing to defence spending targets rising toward 5% of GDP and the EU's ReArm Europe plan aiming to mobilise as much as €800 billion for the bloc's defence-industrial base, copper and silver, the conductive metals at the heart of modern weapons systems, communications, and AI infrastructure, have become as much a security priority as an industrial one. At the same time, record gold prices are adding a further tailwind for precious metals exploration across the continent.
Silver's reputation as a precious metal often overshadows its role as one of the most strategically important industrial metals in the modern economy. Silver is the most electrically and thermally conductive metal known, properties that make it irreplaceable in the high-performance electronics at the centre of AI infrastructure, advanced defence systems, and next-generation energy networks.
The silver market is already in a deep, six-year-long supply deficit, with growth in photovoltaic technology, EVs, and AI data centres expected to widen that gap further. Electric vehicles, 5G infrastructure, semiconductors, and medical devices all rely on silver's unique conductive properties, and in defence, silver is used in guidance systems, communications equipment, radar, and the high-reliability electrical contacts found in virtually every advanced military platform.
For Svea Mining, this structural silver demand significantly enhances the economic case for exploration across properties situated within a district with a long history of copper-silver polymetallic production, where some historical work has also pointed to gold-bearing occurrences, underscoring the broader mineral potential of the Company's land package.
Copper is the backbone of the modern economy, and its importance is accelerating. Often called 'Dr. Copper' for its role as a barometer of economic health, copper is essential to electrification, renewable energy, electric vehicles, the AI revolution, and now Europe's largest defence rebuild since the Cold War. Global copper demand is projected to grow significantly through 2040, with a widening supply deficit expected to persist throughout the decade.
AI data centres are emerging as a major new source of copper demand, requiring copper for wiring, cooling systems, power supply, transmission lines, substations, and grid upgrades. At the same time, modern defence systems — from fighter jets to naval vessels to missile guidance systems — are extraordinarily copper-intensive, layering a new structural source of demand on top of an already strained market.
Svea Mining's strategy of pursuing investments in copper and silver producers alongside its exploration programme is designed to provide shareholders with exposure to the industrial and conductive metals powering electrification, AI, and defence, at a time when the supply-demand fundamentals for both metals have rarely looked stronger.
Gold remains in one of the strongest structural bull markets in modern history. Central banks are buying at the highest sustained pace in decades as they diversify their reserves away from the US dollar, while geopolitical instability, persistent inflation concerns, and fiscal deficits in major economies reinforce demand at every level. According to the World Gold Council, global demand has reached record levels, driven by official-sector purchases, ETF inflows, and retail demand across Asia and Europe.
Major investment banks maintain constructive long-term outlooks, and for explorers, the elevated price environment transforms project economics: historical gold occurrences once considered sub-economic have become highly attractive at today's levels.
For Svea Mining, this backdrop significantly enhances the economic case for exploration across its land package. Both properties lie in and around the Skellefteå district, historically Europe's largest and richest gold-producing region, and historical work has returned gold grades of up to 32 g/t at Stöverfors and 20 g/t at Kalvträsk, none of which has ever been followed up with modern exploration, underscoring the gold potential of the Company's ground.
The Company holds two exploration permits in Västerbotten County, Sweden: Kalvträsk (approximately 7,000 hectares) and Stöverfors (452 hectares). Both properties are located within or on the margin of the Skellefteå VMS belt, a gold, copper and silver bearing geological system with over a century of documented production across the district. Historical work has returned gold grades of up to 32 g/t Au at Stöverfors and 20 g/t Au at Kalvträsk alongside the district's copper-silver signature, pointing to the broader polymetallic potential of the land package.
In addition to its exploration activities, Svea Mining intends to evaluate and pursue strategic investments in gold, copper, silver, rare earth, and other critical metal producers or near-term producers in Europe. This strategy is designed to complement the Company's exploration portfolio with cash-flowing or near-cash-flowing assets, providing revenue diversification and reducing the Company's dependence on exploration outcomes alone.